The Complete Mississauga First-Time Condo Buyer Guide (2026)
Buying your first condo in Mississauga? Learn how to combine the FHSA, HBP, and $4,000 Ontario Land Transfer Tax Rebate, calculate your minimum 5% down payment, and compare Square One vs. Port Credit buildings.
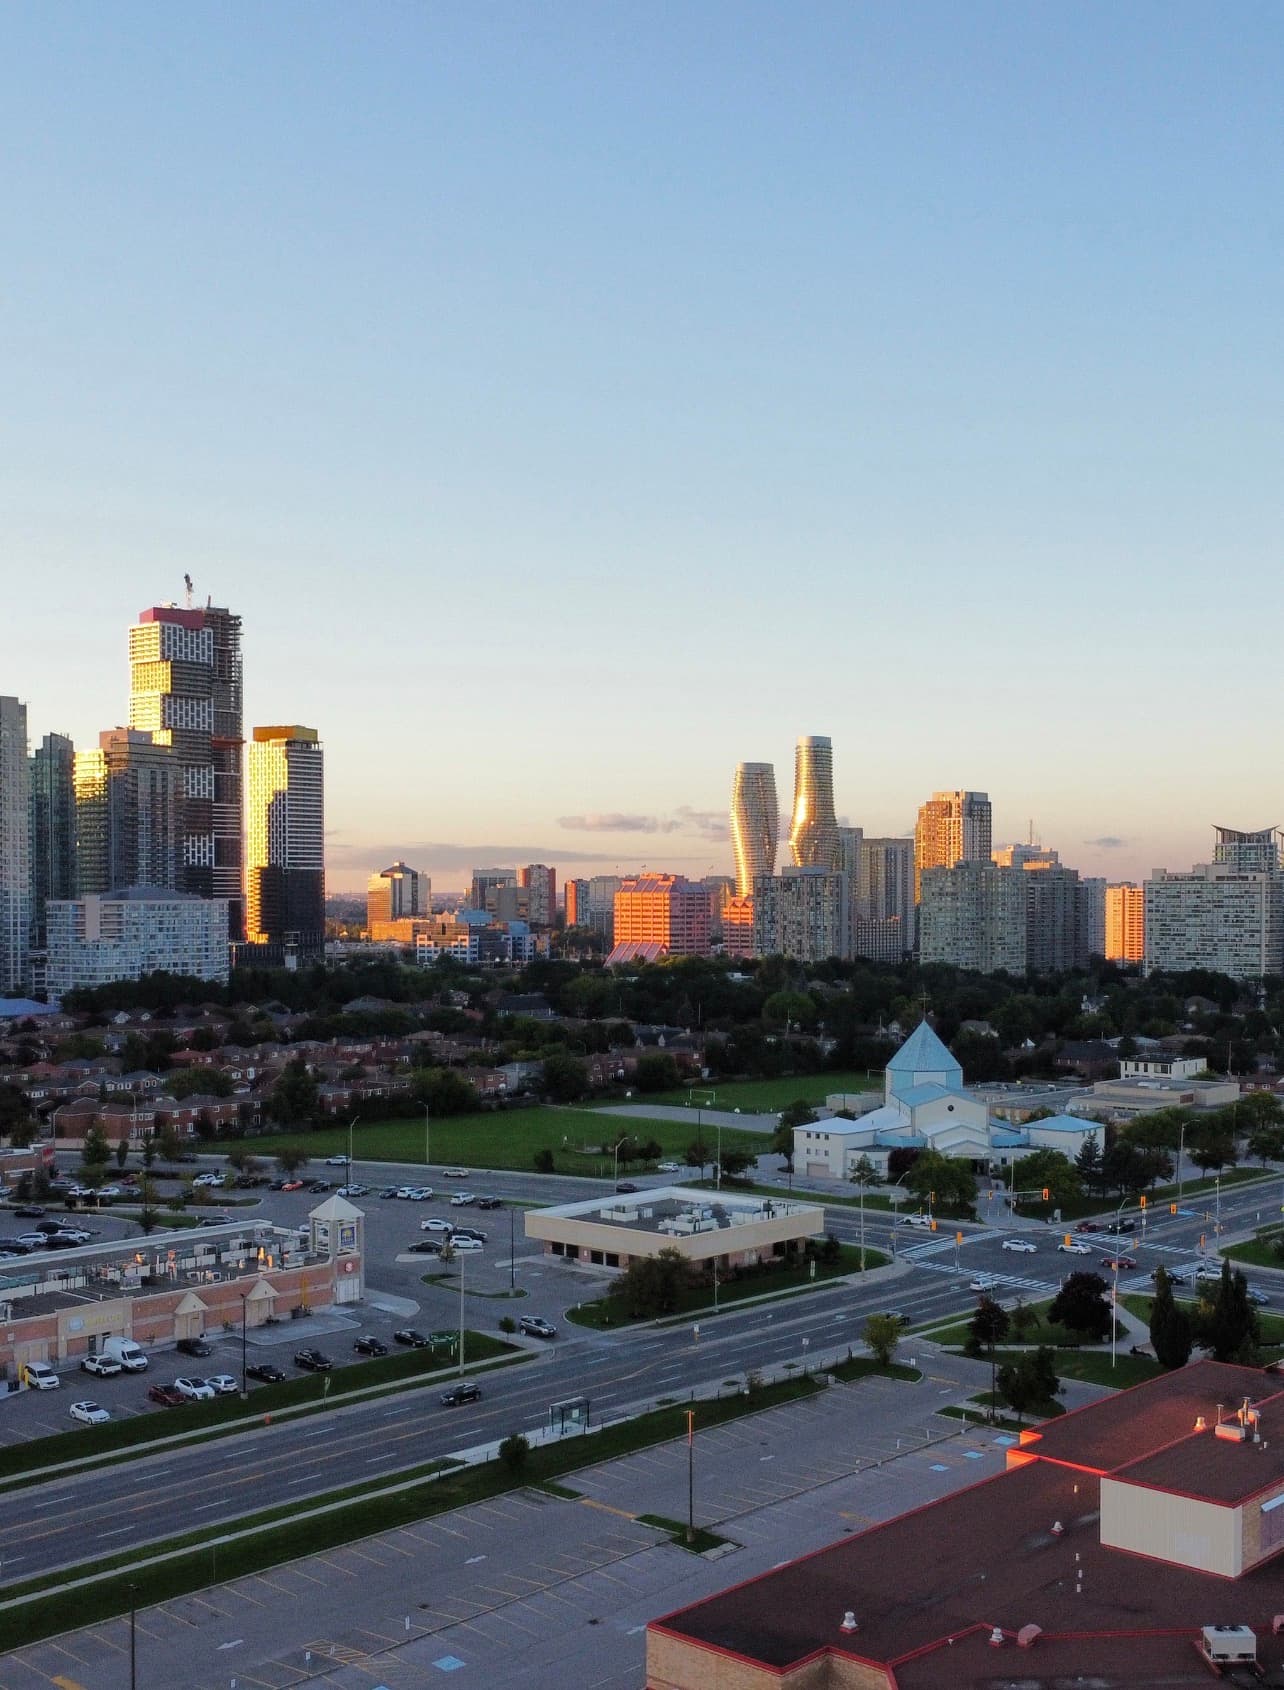
Purchasing your first condominium in Mississauga, Ontario is the most strategic entry point into Greater Toronto Area (GTA) homeownership. While first-time buyers in the City of Toronto face double Land Transfer Taxes and compact studio layouts, Mississauga offers modern master-planned towers, direct GO Transit and Hazel McCallion LRT connectivity, and thousands of dollars in immediate closing cost savings.
Written by Fernando Borges Mora, REALTOR® with eXp Realty, this 2026 Mississauga First-Time Condo Buyer Guide gives you the exact financial math, government rebates, and building-level due diligence needed to buy your first condo with zero guesswork.
1. Every Government Rebate & Tax-Free Program for Mississauga First-Time Buyers (2026)
Before looking at listings, stack every federal and provincial first-time buyer incentive available in Ontario to maximize your down payment and reduce closing tax:
- Ontario Land Transfer Tax (LTT) Rebate (Up to $4,000 Off): First-time home buyers in Ontario who are Canadian citizens or permanent residents receive up to a $4,000 rebate on the Ontario Provincial Land Transfer Tax. Furthermore, because Mississauga is in Peel Region, you pay $0 in Toronto Municipal Land Transfer Tax—saving an extra $7,475 on a $550,000 condo compared to buying in Etobicoke or Downtown Toronto. See the full breakdown in our Mississauga First-Time Buyer Closing Costs Guide.
- First Home Savings Account (FHSA — Up to $40,000 Tax-Free): Contribute up to $8,000 per year ($40,000 lifetime limit per individual, or $80,000 per couple). Contributions are tax-deductible like an RRSP, and withdrawals for your first Mississauga condo are 100% tax-free like a TFSA. Read our FHSA Guide for Mississauga First-Time Buyers.
- RRSP Home Buyers' Plan (HBP — Up to $60,000 Per Buyer): Withdraw up to $60,000 ($120,000 for a couple) tax-free from your existing RRSPs to fund your down payment, with 15 years to repay the balance. Better yet, you can combine the FHSA + HBP on the exact same condo purchase.
- Federal First-Time Home Buyers' Tax Credit (HBTC): Claim a $10,000 non-refundable income tax credit on your annual tax return, providing up to $1,500 in direct federal tax relief after closing.
- 30-Year Insured Mortgage Amortization: Eligible first-time buyers in Canada can now access 30-year amortizations on insured mortgages (under 20% down payment), lowering your mandatory monthly mortgage payment and boosting qualification room.
2. Real Down Payment & Income Math for a Mississauga Condo
How much cash do you actually need in your bank account to buy your first condo in Mississauga? Under Canadian mortgage rules, minimum down payments are tiered:
- 5% Down Payment on the first $500,000 of the purchase price ($25,000).
- 10% Down Payment on the portion between $500,001 and $1,499,999.
- Real Example ($525,000 1-Bedroom + Den Condo near Square One):
- 5% on first $500,000 = $25,000
- 10% on remaining $25,000 = $2,500
- Total Minimum Down Payment = $27,500 (5.24%)
Remember that lenders also apply the OSFI Mortgage Stress Test and include 50% of the condo's monthly maintenance fees plus property taxes when calculating your Gross Debt Service (GDS) ratio. Check exact salary brackets in our guides on Minimum Down Payment in Mississauga and How Much Income You Need to Buy a Condo in Mississauga.
3. Best Mississauga Neighbourhoods & Buildings for First-Time Condo Buyers
Choosing the right pocket protects both your daily lifestyle and future resale value:
- Square One / Downtown Mississauga (City Centre): Best for urban walkability, young professionals, and transit commuters. Explore landmark buildings including 448 Burnhamthorpe Rd W & M City Condos (M1, M2, M3), Absolute World (Marilyn Monroe Towers), and Parkside Village. Read our dedicated Square One First-Time Condo Buyer Guide and Absolute World vs. M City Guide.
- Hurontario Street LRT & Cooksville GO Corridor: Best for value per square foot and rapid transit connectivity along the 18-km Hazel McCallion LRT and Cooksville GO Station. See our Hurontario Condos & LRT Guide.
- Central Erin Mills & Streetsville: Ideal for first-time buyers wanting quieter residential surroundings, proximity to Credit Valley Hospital, and top school districts like John Fraser Secondary School. Explore our Erin Mills Real Estate Guide and Streetsville Village Guide.
- Port Credit & Lakeview Waterfront: Perfect for lifestyle buyers who want Lake Ontario trails and a 25-minute Lakeshore West GO Express commute to Union Station. Compare options in our Port Credit Condo Guide, Lakeview Village Guide, and Humber Bay Shores vs. Mississauga Waterfront Guide.
Debating whether to skip condos and buy a townhome or starter house in Meadowvale or Lisgar? Compare your options in our Condo vs. Townhouse in Mississauga Guide and Lisgar & Meadowvale Homes Guide.
4. The 4 Red Flags First-Time Condo Buyers Must Avoid
Never buy a condo based on staging alone. Before signing an Agreement of Purchase and Sale (OREA Form 101), we protect you against the four costliest first-time buyer mistakes:
- Ignoring What Condo Maintenance Fees Include: A $550/month fee that excludes heat, water, and hydro can cost more monthly than a $680/month fee that includes all utilities. Read our Mississauga Condo Maintenance Fees Guide.
- Skipping the Lawyer Status Certificate Review: Always include a condition allowing your Ontario real estate lawyer to examine the Peel Standard Condominium Corporation (PSCC) Status Certificate and Condo Reserve Fund Study to ensure there are no pending lawsuits or special assessments.
- Assuming Parking & Locker Are Included: Many newer 1-bedroom units in Downtown Mississauga do not include underground parking. We verify legal parking/locker descriptions on the MLS® broker sheet prior to offering.
- Overlooking Kitec Plumbing or Rented HVAC Equipment: In buildings constructed between 1995 and 2007, we check for Kitec plumbing; in newer towers, we verify whether the heat pump is owned or leased ($65–$95/month rental contract). Review our full tour checklist in What to Look For When Buying a Condo in Mississauga.
5. Start Your First Condo Purchase With Fernando Borges Mora, REALTOR®
Remember: in standard Ontario MLS® resale transactions, buyer representation is 100% free (commission is paid by the seller). For personalized first-time buyer guidance in English and Español, connect with Fernando Borges Mora, REALTOR® with eXp Realty: